Buyer Guide · Texas & Oklahoma
The Closing Process: What Happens After Your Offer Is Accepted
Your offer got accepted — congratulations! Here's every step between "yes" and getting the keys, how long each one takes, and how the rules change when the home sits on the Texas or Oklahoma side of the Red River.
Call (580) 217-7435 Search Texoma Homes
Quick answer: after your offer is accepted, a financed purchase usually takes 30 to 45 days to close. In that window you'll deliver earnest money, inspect the home, get an appraisal, clear loan underwriting, clear title, buy homeowners insurance, do a final walkthrough, and sign. Texas buyers usually get an option period with an unrestricted right to walk away; Oklahoma buyers get an inspection period tied to inspection results — and Oklahoma title work runs through an abstract and an attorney's title opinion.
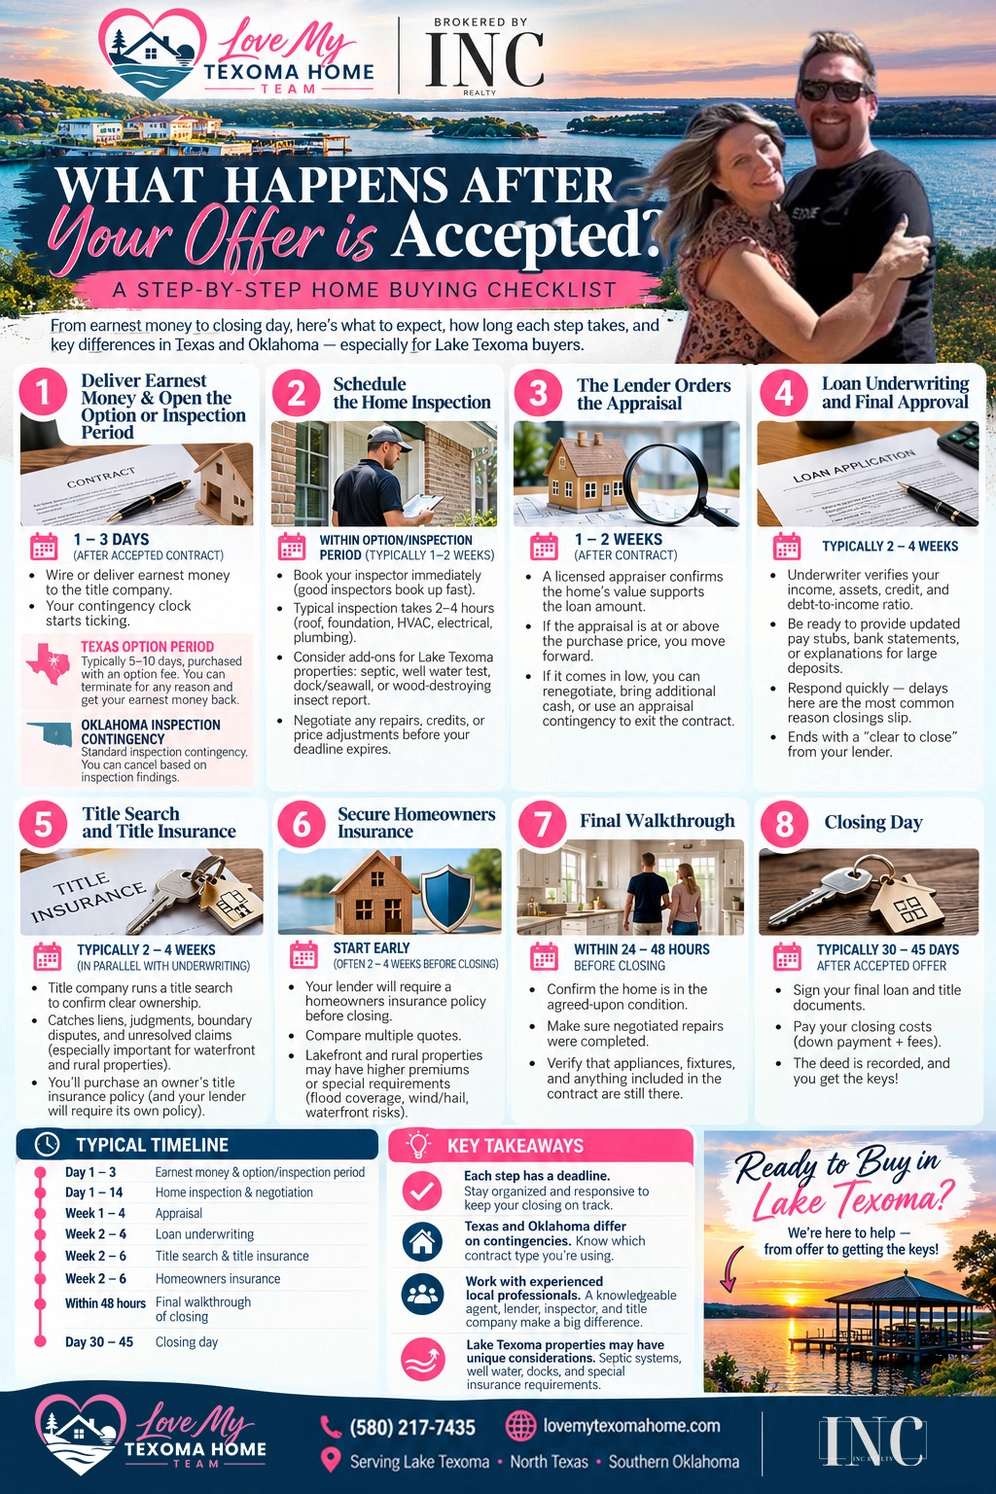
The Closing Process at a Glance
Save or print this checklist and keep it handy while you're under contract. Click the image to open the full-size version.
How long does closing take after an offer is accepted?
For a financed purchase, plan on about 30 to 45 days. Cash purchases can close much faster — often in one to two weeks — because there's no appraisal requirement or loan underwriting, though the title work still has to be finished. Here's how a typical financed timeline lays out. Many of these steps run at the same time, not one after another.
| When | What's happening |
|---|---|
| Day 1–3 | Earnest money (and Texas option fee) delivered; option or inspection period starts |
| Day 1–14 | Home inspection, any specialty inspections, repair negotiation |
| Week 1–4 | Appraisal ordered and completed |
| Week 2–6 | Loan underwriting and final approval ("clear to close") |
| Week 2–6 | Title search, title commitment (TX) or abstract & title opinion (OK) |
| Week 2–6 | Homeowners insurance bound (flood coverage if needed) |
| 3 business days before | Closing Disclosure delivered by your lender |
| Within 24–48 hours | Final walkthrough |
| Day 30–45 | Closing day — sign, fund, record, keys |
01 · Deliver Earnest Money & Start Your Option or Inspection Period
⏱ Within 3 days of the accepted contract
The clock starts the moment the contract is fully signed. Your first job is getting your earnest money to the title company (or other escrow holder named in the contract). Earnest money shows the seller you're serious, it's held in trust — not handed to the seller — and it's credited toward your down payment and closing costs at the closing table.
Both states' standard contracts give you a short window: Texas's TREC One to Four Family Residential Contract and Oklahoma's OREC Residential Contract of Sale each call for earnest money within 3 days, with deadlines that land on a weekend or legal holiday rolling to the next business day. Miss it and you can lose important rights, so we'll usually set up delivery the same day you go under contract.
🤠 In Texas
Along with earnest money, Texas buyers usually pay a separate option fee directly toward the seller. That buys an option period — a negotiated number of days (often 5 to 10 in our market) when you can terminate for any reason by written notice before 5:00 p.m. on the last day and get your earnest money back. The option fee itself isn't refunded, and if it isn't delivered on time, you lose that unrestricted right to walk away.
🌾 In Oklahoma
Oklahoma's contract uses an inspection period instead — 10 days after the contract's Time Reference Date if the blank is left empty. You inspect, then either cancel because the results aren't acceptable, or send the seller a list of requested treatments, repairs, and replacements. It's tied to what the inspections find rather than an any-reason exit, and doing nothing during the period counts as accepting the property.
Want to know which protections to build into your offer in the first place? Read What Contingencies to Include When Buying on Lake Texoma.
02 · Schedule the Home Inspection
⏱ Inside the option or inspection period — usually the first week
Book your inspector the same day you go under contract. Good inspectors around {a('/sherman-tx', 'Sherman')}, {a('/denison-tx', 'Denison')}, and {a('/durant-ok', 'Durant')} fill up fast, and your option or inspection deadline doesn't move just because the calendar is full. A standard inspection of a typical home takes about 2 to 4 hours and covers the roof, foundation, HVAC, electrical, plumbing, and visible structure.
Two local inspectors we've featured: Blue Brick Inspections in Denison and A Realistic Home Inspection in southeast Oklahoma.
Add-on inspections worth considering in Texoma:
- Septic system — very common outside city limits on both sides of the lake (see the kinds of septic systems in Oklahoma)
- Well water test — for rural and acreage homes on private wells
- Wood-destroying insect (termite) report — often lender-required, smart either way
- Dock, seawall, or boathouse — for waterfront homes (see the lake section below)
- Foundation engineer — our clay soils move, so a second look is cheap insurance when the inspector flags movement
🤠 In Texas
Once you have the reports, negotiation happens inside the option period — a repair amendment, a price reduction, a credit toward closing costs, or a walk-away if you can't agree. If the lender requires repairs that cost more than 5% of the sales price, the TREC contract gives the buyer a right to terminate.
🌾 In Oklahoma
You have 24 hours after the inspection period ends to deliver the reports to the seller with your request. Then there's a negotiation period — 7 days if the contract leaves it blank. If you can't reach agreement, the contract ends and your earnest money comes back to you, unless you choose to accept the property as-is.
Need a recommendation? Our Texoma Lenders & Local Pros page lists inspectors we trust.
03 · The Lender Orders the Appraisal
⏱ Ordered in week 1–2; report often back in 1–2 weeks
If you're financing, your lender orders an appraisal from a licensed appraiser to confirm the home is worth at least what the loan is based on. You don't pick the appraiser and you don't attend — but you usually pay for it, often up front.
- Appraisal at or above the price: great — you keep moving.
- Appraisal comes in low: you can ask the seller to lower the price, bring extra cash to cover the gap, split the difference, challenge the value with better comparable sales, or — if your contract has an appraisal contingency — walk away with your earnest money.
Lake and rural properties are where appraisal gaps show up most, because truly comparable sales (same water frontage, same acreage, same dock setup) can be scarce. That's one reason we pull comps carefully before you ever write the offer.
04 · Loan Underwriting & Final Approval
⏱ Typically 2–4 weeks, running alongside everything else
Underwriting is where the lender double-checks everything: your income, assets, credit, debts, the appraisal, and the title work. Expect requests for updated pay stubs, recent bank statements, and written explanations of large deposits. The faster you answer, the faster you get to "clear to close."
While you're under contract, don't:
- Open new credit cards or finance furniture, a truck, or a boat
- Change jobs or switch from salary to commission without telling your lender first
- Move large sums between accounts or make cash deposits you can't document
- Co-sign a loan for anyone
Three business days before closing, your lender must give you the Closing Disclosure — the final numbers for your loan and cash to close. Compare it line by line with your Loan Estimate. Per the Consumer Financial Protection Bureau, a new three-day review period is required only if the APR rises beyond set limits, a prepayment penalty is added, or the loan product changes.
Exploring down payment help? See First-Time Home Buyer Programs in Texoma. Using an FHA loan? Our FHA loan guide for Texoma buyers covers what lenders review, and you can find a local lender here.
05 · Title Search & Title Insurance
⏱ Typically 2–4 weeks, in parallel with underwriting
Title work proves the seller actually has the right to sell you the property, free of surprise liens, judgments, unpaid taxes, boundary problems, or missing heirs. This is the step where Texas and Oklahoma differ the most.
🤠 In Texas
A title company searches the records and issues a title commitment — under the TREC contract, within 20 days after the title company receives the contract. You then have a set number of days to object to problems, and the seller gets a cure period. Title insurance premiums in Texas are set by the state, so the base rate is the same no matter which title company you use (Stewart Title, Texas practices). Who pays for the owner's policy is a checkbox in the contract; in North Texas it's common for the seller to pay it, but it's negotiable.
🌾 In Oklahoma
Oklahoma is an abstract state. A bonded abstract company updates the property's abstract of title — its ownership history going back to statehood — and an Oklahoma-licensed attorney examines it and issues a title opinion before a title commitment or policy can be issued (Stewart Title, Oklahoma practices). Under the OREC contract, the seller typically pays for the abstract, and you get 10 days after receiving the title evidence to object. Title insurance rates in Oklahoma aren't state-set, so they can vary by company. See how a local abstract company works in our profile of Marshall County Abstract Company in Madill.
Either way, buy the owner's title policy. Your lender's policy protects only the lender. The owner's policy protects your equity, and on waterfront and rural land — where old easements, mineral reservations, and fuzzy boundary lines are common — it earns its keep.
Surveys: Texas contracts let the parties use the seller's existing survey with an affidavit (form T-47) or order a new one. In Oklahoma you can choose a Mortgage Inspection Report or a full pin-stake boundary survey. On acreage or anything with a fence line that looks "approximate," we almost always recommend a real boundary survey.
06 · Secure Homeowners Insurance
⏱ Start in week 1 — bind it 2–4 weeks before closing
Your lender won't fund the loan without proof of homeowners insurance, and in Texoma the quote can surprise people. Wind and hail deductibles are often a percentage of the home's value, roofs get scrutinized by age, and some carriers limit how much new business they write.
- Get at least two or three quotes in the first week — don't wait for clear to close.
- Check the flood zone on FEMA's Flood Map Service Center. If the lender says flood insurance is required, budget for it before you finalize your offer strategy.
- Ask about separate coverage for boathouses, docks, detached shops, and barns — they're not always included. Need a local agent? Meet The Brawley Agency.
- Insurance is a Buyer expense under the TREC contract (flood and hazard premiums), and that's the norm in Oklahoma too.
07 · The Final Walkthrough
⏱ Within 24–48 hours before closing
The walkthrough isn't another inspection — it's your chance to confirm the home is in the condition you agreed to buy. Both states' contracts expect the property to be in the same condition as when the contract was signed, except normal wear and the agreed repairs.
- Make sure agreed repairs were actually completed — ask for receipts and any warranties
- Run every faucet, flush every toilet, and test the HVAC, appliances, and garage doors
- Confirm anything the contract says stays (refrigerator, dock equipment, window units, outbuilding contents) is still there
- Look for new damage from the move-out — wall dings, floor scratches, a leak under the sink
If something's wrong, call us before you sign anything. It's much easier to fix with a repair credit or holdback at the closing table than after the deed records.
08 · Closing Day
⏱ Typically 30–45 days after the accepted offer
You'll sign the loan documents and the closing statement, bring your funds (by verified wire or cashier's check — never by instructions you only received by email), and the seller signs the deed. Once the lender funds and the deed is recorded with the county clerk, the home is yours.
- Bring a government-issued photo ID
- Bring your verified funds for the "cash to close" amount on your Closing Disclosure
- Confirm when you get the keys — possession is usually at closing and funding, but your contract may say otherwise
- Keep a copy of every document you sign
In Oklahoma, the seller pays the documentary stamp tax on the deed when it's recorded. Texas has no state real estate transfer tax.
What's different about closing in Texas vs. Oklahoma?
We sell on both sides of the Red River every month, and these are the differences buyers notice most. Contract numbers below reflect each state's current standard forms when left at their defaults — your actual contract may set different days, and your title company or a real estate attorney is always the final word.
| Item | 🤠 Texas | 🌾 Oklahoma |
|---|---|---|
| Standard contract | TREC One to Four Family Residential Contract (Resale) | OREC Residential Contract of Sale |
| Earnest money due | Within 3 days of the effective date | Within 3 days of full execution |
| Your exit right | Option period — terminate for any reason (option fee paid) | Inspection period — cancel or negotiate based on inspection results |
| Repair negotiation | Inside the option period, by amendment | Request list within 24 hours after inspection period; 7-day negotiation if blank |
| Title evidence | Title commitment from a title company | Abstract + attorney title opinion, then commitment/policy |
| Title insurance rates | Set by the state (same base rate everywhere) | Not state-set; can vary by company |
| Survey | Existing survey + T-47 affidavit, or new survey | Mortgage Inspection Report or pin-stake boundary survey |
| Transfer tax | None | Documentary stamps: $0.75 per $500, paid by the seller |
| Seller disclosure | Seller's Disclosure Notice (Tex. Prop. Code §5.008) | Residential Property Condition Disclosure or Disclaimer |
| Lake-specific notice | Water-level fluctuation notice for property next to a large reservoir | No equivalent standard contract notice |
| Homestead exemption | $140,000 off school taxes; apply by April 30 | $1,000 off assessed value; apply by March 15 |
Shopping both states? Our Buying a Home in Texoma guide walks through the whole search, and our Texoma Real Estate FAQ answers the most common two-state questions.
What extra steps come with a lake or rural home?
A home on or near Lake Texoma or on rural acreage adds a few items to the checklist that city buyers never think about:
- Dock permits don't transfer automatically. Private docks on Corps of Engineers water need a Shoreline Use Permit, and federal rules make those permits non-transferable — when the home sells, the new owner has to apply for their own (36 CFR §327.30). Ask for the current permit early and confirm the dock is in an area where private docks are allowed. Read the Army Corps dock permitting process and the history of the dock permit moratorium.
- The Corps owns the shoreline, not you. Most lake-area homes stop at a government property line short of the water. Know where that line is before you plan a fence, a mowed path, or a new boat ramp. See where the Corps ownership line falls and whether you can cut trees on Corps land.
- Water levels move. Texas contracts include a notice that the level of a large adjoining reservoir fluctuates. Lake Texoma's level has swung from drought lows to the record 2015 flood, when water topped the dam's spillway.
- Septic and wells. Have the septic system evaluated and the well water tested. Oklahoma State University's land buyer's septic guide and the TCEQ on-site sewage program explain what to look for on each side of the river.
- Insurance and flood zones. Waterfront homes may need flood coverage and separate coverage for docks and boathouses — start shopping in week one.
Thinking about life on the water? Read Living the Lake Life for what owning near Lake Texoma is really like.
What closing costs should buyers expect?
Buyers typically pay roughly 2% to 5% of the purchase price in closing costs on top of the down payment, depending on the loan, the lender's fees, prepaid items, and what you negotiate with the seller. Your Loan Estimate shows the expected numbers within three business days of applying, and your Closing Disclosure shows the final ones.
Common buyer costs
- Loan origination and underwriting fees
- Appraisal and credit report
- Lender's title policy
- Prepaid interest, insurance, and property-tax escrow
- Recording fees and your share of escrow/closing fees
- Inspections and survey (if you're paying)
Commonly paid by the seller
- Their mortgage payoff and lien releases
- Owner's title policy (common in North Texas — negotiable)
- Abstract update (Oklahoma)
- Documentary stamp tax (Oklahoma)
- Deed preparation
- Prorated property taxes through the closing date
Sellers can also contribute toward your closing costs if you negotiate it in the offer. We'll run a buyer cost estimate with you before you write any offer.
🔒 Protect your closing money from wire fraud
Scammers watch for home sales and send fake "updated wiring instructions" that look exactly like they came from your agent or title company. Once the money is gone, it's very hard to get back.
- Never wire money based on instructions in an email or text — even if it looks like it's from us.
- Call the title company at a phone number you already verified (not the one in the email) to confirm the account before you send anything.
- Our team will never email you new or changed wiring instructions.
- If something feels off, stop and call us at (580) 217-7435. If you've already sent money, call your bank immediately to request a recall and report it at ic3.gov.
More tips from the Consumer Financial Protection Bureau.
What should I do right after closing?
- File your homestead exemption. In Texas, school districts must offer a $140,000 homestead exemption, applications are generally due before May 1, and if you buy mid-year you may qualify for the rest of that year if the previous owner didn't claim it (Texas Comptroller). In Oklahoma, you must own and live in the home by January 1 and apply with the county assessor by March 15 for a $1,000 reduction in assessed value (see this county assessor guide).
- Set up utilities. Our Texoma Utility Guide lists electric, water, gas, trash, and internet providers town by town.
- Change the locks and garage codes on day one.
- Store your closing package and owner's title policy somewhere safe — you'll want them for taxes, refinancing, and someday selling.
- Watch for mail scams offering to send you a copy of your deed for a fee. Your recorded deed is a public record you can get from the county clerk.
Closing process FAQ
Can I back out after my offer is accepted?
Usually, but only under the contract's terms. In Texas, the option period lets you terminate for any reason if you paid the option fee on time. In Oklahoma, you can cancel during the inspection period based on unsatisfactory inspection results. Financing and appraisal contingencies, title objections, and disclosure rules can also give you exits. Outside those protections, walking away can cost you your earnest money.
Do I get my earnest money back if the deal falls through?
It depends on why. If you terminate within a contract right — the Texas option period, an Oklahoma inspection cancellation, a financing or appraisal contingency — your earnest money is generally refunded. If you simply default, the seller may be entitled to keep it.
What does "clear to close" mean?
It's your lender's sign-off that underwriting is finished and every loan condition is satisfied. Once you're clear to close, the lender sends the final documents to the title company and the Closing Disclosure is issued.
How much earnest money is normal in Texoma?
It varies by price point and competition, but about 1% of the purchase price is common. It's credited back to you at closing toward your down payment and costs. New to buying? Start with our 10 home buying tips for new buyers in Texoma.
Why does Oklahoma use an abstract?
Oklahoma title practice is built on the abstract of title — a compiled history of every recorded document affecting the land since statehood. An attorney reviews it and issues a title opinion, which the title insurer relies on. It's one reason Oklahoma closings can need a little more lead time.
Can a cash buyer close faster?
Yes. Without an appraisal requirement or loan underwriting, a cash closing can happen in about one to two weeks, as long as the title work and any inspections are done.
Do I need my own agent if the listing agent offers to help?
The listing agent represents the seller. Having your own agent means someone is reading every deadline, inspection report, and title objection with only your interests in mind. Learn more about working with a local Realtor.
Planning a home purchase in Texoma?
Whether you're just starting to look or getting ready to write an offer, we'd love to help you find the right home in Sherman, Denison, Durant, Kingston, or anywhere around the lake — and walk you through every step from first showing to closing day. Already working with an agent? Feel free to share this guide with them.
Call (580) 217-7435 Search Texoma HomesSources
- Texas Real Estate Commission — One to Four Family Residential Contract (Resale), Form 20-18
- Oklahoma Real Estate Commission — 2026 Residential Contract of Sale
- Stewart Title — Texas Real Estate Practices
- Stewart Title — Oklahoma Real Estate Practices
- Johnston County, OK — County Clerk Fees (documentary stamp rate)
- CFPB — You'll get 3 days to review your mortgage closing documents
- CFPB — Mortgage closing scams: how to protect yourself and your closing funds
- Texas Comptroller — Property Tax Exemptions
- Canadian County, OK Assessor — Homestead Exemption
- 36 CFR §327.30 — Corps of Engineers Shoreline Management
- FEMA Flood Map Service Center
This guide is general information, not legal advice. Every contract is different — your title company, lender, or a real estate attorney is the final word on your transaction. Love My Texoma Home Team, a team of INC Realty.