Buyer Guide · Oklahoma & Texas · Updated October 2026
Native American Homebuyer Programs in Oklahoma: The Complete 2026 Guide to Tribal Benefits & the Section 184 Loan
Every Oklahoma tribal homebuyer program in one place: what it pays, who qualifies, and the exact link to apply. Plus a deep dive on the HUD Section 184 home loan and how it works on both sides of the Red River.
Call (580) 217-7435 Search Texoma Homes
Quick answer: if you're an enrolled member of any federally recognized tribe, you can buy a home in Oklahoma, and in 16 approved Texas counties, with as little as 2.25% down using the HUD Section 184 loan. There's no monthly mortgage insurance and no income limit. You can stack a tribal down payment grant on top, which runs from about $2,000 to $20,000 depending on your tribe (HUD) (Cherokee Nation HACN).
Why we wrote this guide (and why it's personal)
Here's the line I tell every client: buying a home is no small feat. It's likely the largest financial move you'll ever make. The good news for Native buyers is that there's more help on the table than most people realize, and most of it goes unused. Section 184 has backed more than 56,000 loans since it started, yet at one of Oklahoma's biggest banks it made up only about 1% of home loans (Federal Register, 2024) (Bank of Oklahoma).
This one is personal for me. I'm Brian Allen, and I'm a card-carrying citizen of the Chickasaw Nation. I've used many of the Nation's benefits myself, so I know what it's like to dig through tribal websites, chase paperwork and wonder which program fits. As a Realtor with Love My Texoma Home, I walk Native buyers across Durant, Ardmore, Sherman and the rest of Texoma through the same steps I took. New to buying? Start with our first-time home buyer guide for Texoma too.
Key takeaways
- Section 184 is the foundation. 2.25% down on loans over $50,000 (1.25% under), a 1% upfront fee you can roll into the loan, no monthly mortgage insurance on loans closed since July 1, 2023, and no income limit (HUD).
- All of Oklahoma qualifies. In North Texas, Grayson, Fannin and Collin counties qualify; Cooke County does not (HUD map, June 2026).
- Your tribe, not where you live, decides most grants. Chickasaw citizens can get a down payment grant even if they live in Texas. Cherokee, Muscogee (Creek) and Seminole help only applies to homes inside those reservations (Chickasaw Nation) (HACN).
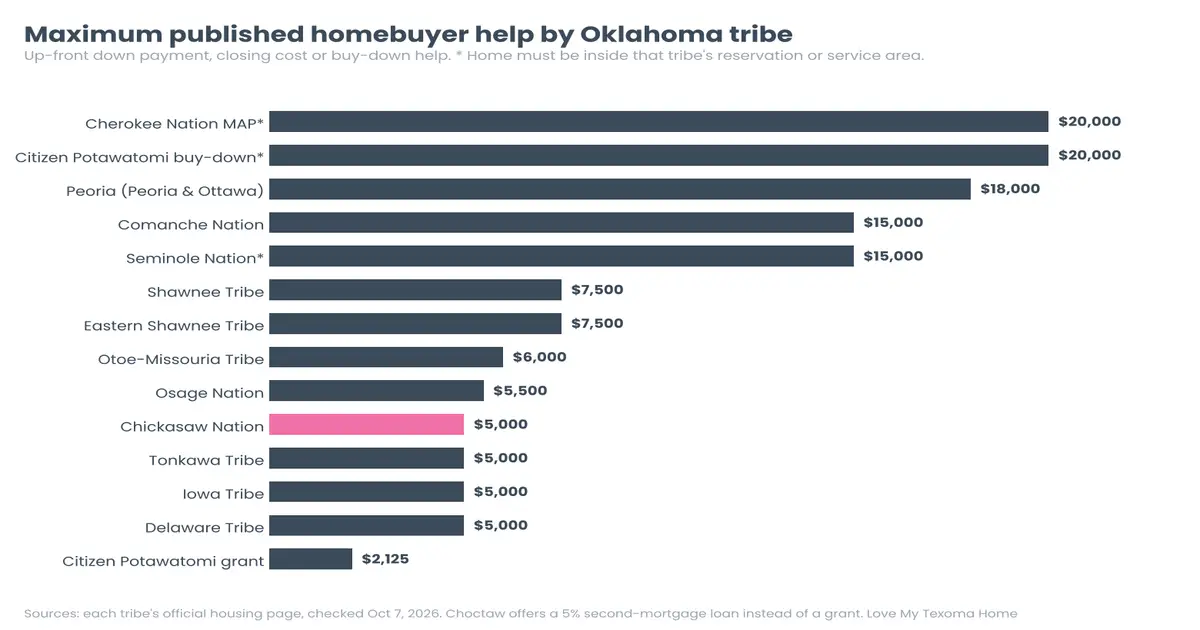
- The biggest grants: Cherokee MAP up to $20,000, Citizen Potawatomi buy-down $20,000, Peoria up to $18,000, Comanche and Seminole up to $15,000.
- Get pre-approved first. Almost every tribal grant needs a lender approval letter, several need paperwork 3 to 6 weeks before closing, and grants are never paid after closing.
Who qualifies for Native American homebuyer programs?
You qualify for Section 184 if you're a currently enrolled member of a federally recognized tribe and the home will be your primary residence in an approved area. Your tribe confirms enrollment; HUD and lenders can't do it for you (HUD). Since October 6, 2025, the borrower must also be a U.S. citizen or lawful permanent resident (Federal Register 2025-16979).
Tribal grants add their own rules on top. The four that come up most:
- Citizenship in that specific tribe. Chickasaw, Choctaw, Tonkawa and Shawnee Tribe help is for their own citizens. Cherokee MAP, Seminole and Osage help is open to members of any federally recognized tribe, with preference for their own citizens.
- Income. Most programs paid for with federal NAHASDA money cap income at 80% of median. For 2026, Cherokee Nation's limit runs from $59,850 for one person to $85,450 for a family of four (HACN). Chickasaw's grant and Choctaw's CHAP loan list no income limit.
- Location. Some programs follow the tribal citizen anywhere. Others only pay for homes inside the reservation or service area.
- First-time buyer. Usually defined as no home owned in the past 2 or 3 years. Not every program requires it.
CDIB vs. tribal enrollment card
These are two different documents. A tribal citizenship or enrollment card proves you're a member, and that's what Section 184 lenders ask for. A Certificate of Degree of Indian Blood (CDIB) is a Bureau of Indian Affairs certificate showing your blood quantum. Some tribal programs still ask for it (Chickasaw Nation CDIB application). Getting one takes an original state-issued long-form birth certificate and notarized lineage paperwork, so start early. Chickasaw citizens can call Tribal Government Services at (580) 436-7250.
Documents to gather before you apply
| Document | Who usually asks for it |
|---|---|
| Tribal enrollment or citizenship card (front and back) | Section 184 lender and every tribal program |
| CDIB | Some tribal programs (Kiowa, Choctaw Section 184 desk, Muscogee preference) |
| Photo ID and Social Security card for every borrower | Everyone |
| Last 30 days of pay stubs, 2 years of W-2s and tax returns | Lender and tribal programs |
| Award letters (SSI, retirement, VA) | Lender, if you have that income |
| 2 months of bank statements | Lender; Chickasaw housing counseling |
| 2 years of rental or mortgage history | Choctaw Home Finance, LEAP |
| Lender pre-approval letter and loan application with the property address | Chickasaw, Osage, Iowa and most other grants |
| Homebuyer education certificate | Cherokee MAP, Seminole, Comanche (required); recommended for Section 184 |
Sources: (HUD Section 184) (Choctaw Nation) (Chickasaw grant) (Kiowa Housing Authority)
The Section 184 home loan: the complete guide 🔑
The Section 184 Indian Housing Loan Guarantee Program is a HUD mortgage built only for enrolled members of federally recognized tribes. It lets you buy with 2.25% down, skips monthly mortgage insurance, and has no income cap. For most Native buyers in Oklahoma, it's the best first mortgage available (HUD).
What is a Section 184 loan?
Congress created Section 184 in 1992 because mainstream lenders were barely lending in Indian Country (FDIC Affordable Mortgage Lending Guide). HUD's Office of Native American Programs guarantees 100% of the loan to the lender. That guarantee is what lets lenders offer a low down payment and look past a thin or bruised credit file.
You don't borrow from HUD. You borrow from a regular bank or mortgage company on HUD's approved list, and HUD stands behind the loan. Since 1994 the program has guaranteed more than 56,000 loans worth over $10 billion, and it now averages about 2,500 loans a year (Federal Register, March 20, 2024).
Section 184 benefits at a glance
| Feature | Section 184 terms |
|---|---|
| Down payment | 2.25% on loans over $50,000; 1.25% on loans of $50,000 or less |
| Upfront guarantee fee | 1% one time, can be financed into the loan |
| Monthly mortgage insurance | None on loans closed on or after July 1, 2023 |
| Income limit | None |
| Interest rate | Fixed, market-based, not priced by your credit score |
| Adjustable-rate loans | Not allowed |
| Loan term | Up to 30 years |
| Minimum credit score | None published; underwriting is done by hand |
| Debt-to-income limit | 41%, or up to 43% with 2 or more strengths like reserves or strong credit |
| Property | 1 to 4 units, your primary residence |
| Prepayment penalty | None |
Sources: (HUD Section 184 borrowers page) (HUD Processing Guidelines Ch. 2-B) (FDIC guide, debt ratio).
What you can use a Section 184 loan for
- Buy an existing home, including townhomes, condos in FHA-approved projects, and modular or manufactured homes on a permanent foundation
- Build a new home with a single-close construction loan (see new construction in Texoma)
- Buy and fix up a home in one loan, or rehab one you own (weatherization counts)
- Refinance: rate-and-term, streamline, or cash-out
- Assume an existing Section 184 loan
- Buy a duplex, triplex or fourplex and live in one unit; the rent from the other units can help you build wealth
You can't use it for a second home, a lake house you won't live in, or a pure investment property (HUD).
Who can borrow
- At least one borrower must be an enrolled tribal member. A co-borrower doesn't have to be Native, and their income still counts (BOK Financial, 2025).
- A family member who won't live in the home can co-sign as a non-occupant co-borrower if related by blood or in a long-standing family-type relationship (24 CFR 1005.403).
- One Section 184 loan per family at a time, with a narrow exception for co-signing (Federal Register, 2024).
- U.S. citizen or lawful permanent resident, effective October 6, 2025 (Federal Register 2025-16979).
Where you can use it in Texoma
Tribes choose which areas are eligible, and the map now reaches far beyond trust land. As of HUD's June 2026 map (DLL 2026-04 map):
- Oklahoma: every county, including Durant, Calera and Colbert in Bryan County; Kingston and Madill in Marshall County; Ardmore in Carter County; Tishomingo in Johnston County; Atoka; Coalgate; Hugo; and Antlers.
- Texas: Grayson County (Sherman, Denison, Pottsboro, Van Alstyne), Fannin County (Bonham) and Collin County (McKinney, Frisco, Plano).
- Not approved: Cooke County (Gainesville). Look at FHA or USDA there instead.
Buying on restricted or allotted land? Order a title status report from the BIA first. On trust land, you'll need a lease through your tribe (HUD). Buying acreage? Read how to buy land near Lake Texoma.
2026 Section 184 loan limits
For 2026, HUD ties Section 184 limits to FHA's 2026 limits (DLL 2026-02). For a single-family home, most Oklahoma counties plus Grayson and Fannin sit at the $541,287 floor (HUD), and Collin County is $563,500 (LendingTree). Confirm your county's figure with your lender.
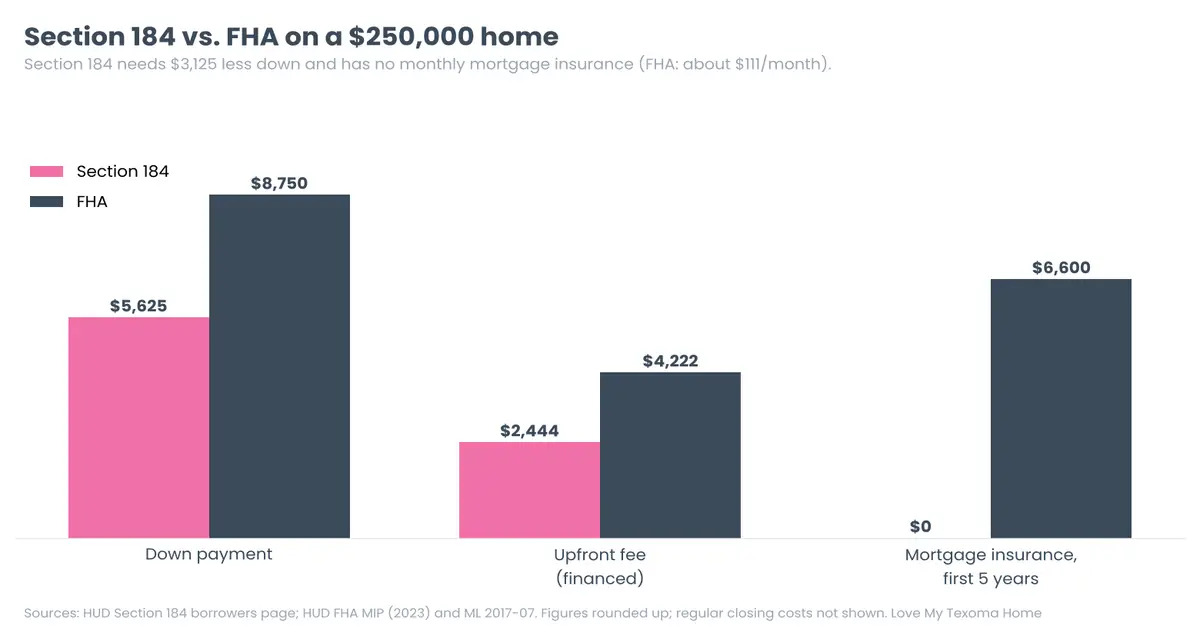
What it costs: Section 184 vs. FHA on a $250,000 home
| Section 184 | FHA | |
|---|---|---|
| Down payment | $5,625 (2.25%) | $8,750 (3.5%) |
| Upfront fee | $2,444 (1%), financed | $4,222 (1.75%), financed |
| Monthly mortgage insurance | $0 | about $111 (0.55% a year) |
| Mortgage insurance, first 5 years | $0 | about $6,600 |
Cash at closing is $3,125 less with Section 184, and you save about $111 every month. Figures are rounded up; both loans also have regular closing costs. FHA's 0.55% annual premium is from (HUD, 2023) and the 1.75% upfront premium from (HUD ML 2017-07). For the full FHA picture, see Is an FHA Loan Right for You?, and browse homes from $200K to $300K.
Why Section 184 is a solid choice for Native buyers
- Less cash to get in the door. 2.25% down is lower than FHA's 3.5%, and tribal grants can cover much of the rest.
- No monthly mortgage insurance. It's the single biggest monthly saving over FHA and most low-down-payment conventional loans.
- Your rate isn't punished for your credit score. Rates are market-based, not tiered by score, and there's no published minimum score (HUD).
- A real person reviews your file. Manual underwriting can approve borrowers that automated systems reject, like those with short credit histories or seasonal income.
- No income cap. A high-earning household qualifies the same as a first-time buyer.
- It works where other loans don't. It's one of the few mortgages that can be made on trust and restricted land.
- It stacks with tribal help. Gifts and down payment assistance from a tribe or family are allowed (FDIC guide), and Choctaw Home Finance pairs its 5% second mortgage with Section 184 (Choctaw Nation).
The honest downsides
- Manual underwriting takes longer. Plan on more paperwork and answer document requests fast.
- Primary residence only, one loan at a time. Not for lake getaways or rentals.
- Debt ratio is tight. 41% is lower than FHA allows, so pay down car loans and cards before you apply.
- Some state down payment programs won't pair with it. OHFA and TDHCA list only FHA, VA and USDA first mortgages (OHFA guide) (TDHCA matrix).
- Fewer lenders know it well. Ask how many Section 184 loans a lender closed last year.
What's changing: the 2024 Section 184 rule
HUD published its first major rewrite of the program on March 20, 2024, adding lender standards, foreclosure protections and a requirement that servicers try a loan modification before foreclosing (Federal Register) (Tribal Business News). On December 29, 2025, HUD pushed the compliance date back indefinitely until it finishes a new handbook (Federal Register 2025-23884) (DLL 2026-01). Until then, lenders follow the existing guidelines, so the terms above still apply.
How to apply for a Section 184 loan, step by step
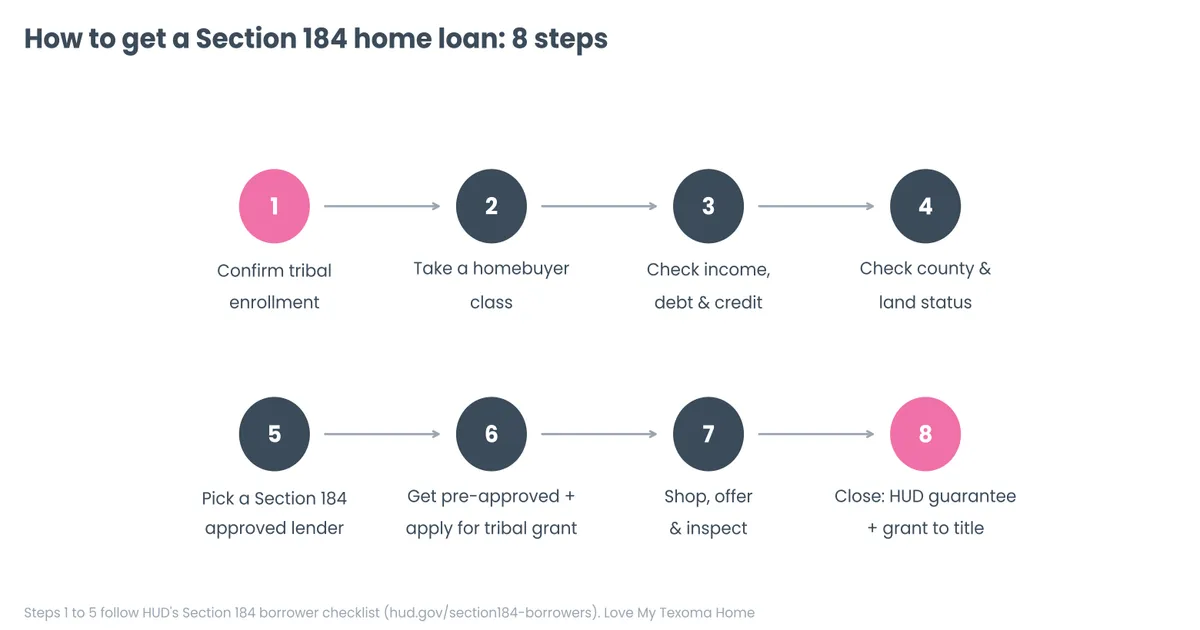
- Confirm your enrollment. Have your tribal citizenship card in hand. Lenders can't verify membership for you.
- Take a homebuyer class. It's free through your tribe or a (HUD-approved counselor). Section 184 doesn't require it, but many tribal grants do.
- Do a self-check. Look at your income, debts and credit, and pull your free reports at AnnualCreditReport.com. Don't open new credit. Our 10 home buying tips for new Texoma buyers covers the rest of the prep.
- Check the property's location and land status. Make sure the county is on (HUD's approved map). On allotted or trust land, order a BIA title status report.
- Pick a Section 184 approved lender. HUD's August 2026 list shows 179 lenders approved in Oklahoma or Texas (HUD lender list). See our partner lenders who can do Section 184 below.
- Get pre-approved, then apply for your tribe's down payment help right away. Chickasaw wants documents at least 3 weeks before closing.
- Shop, offer and inspect with a buyer's agent who knows these programs. See how to work with a local Realtor and which contingencies to include, then search all Texoma homes.
- Close. Your lender sends the file to HUD for the guarantee, and your tribal grant is wired to the title company. Here's how closing works in Texas and Oklahoma.
Steps 1 to 5 follow HUD's own checklist (HUD). Questions HUD can answer directly: [email protected].
Can you use a Native American home loan in Texas? 🤠
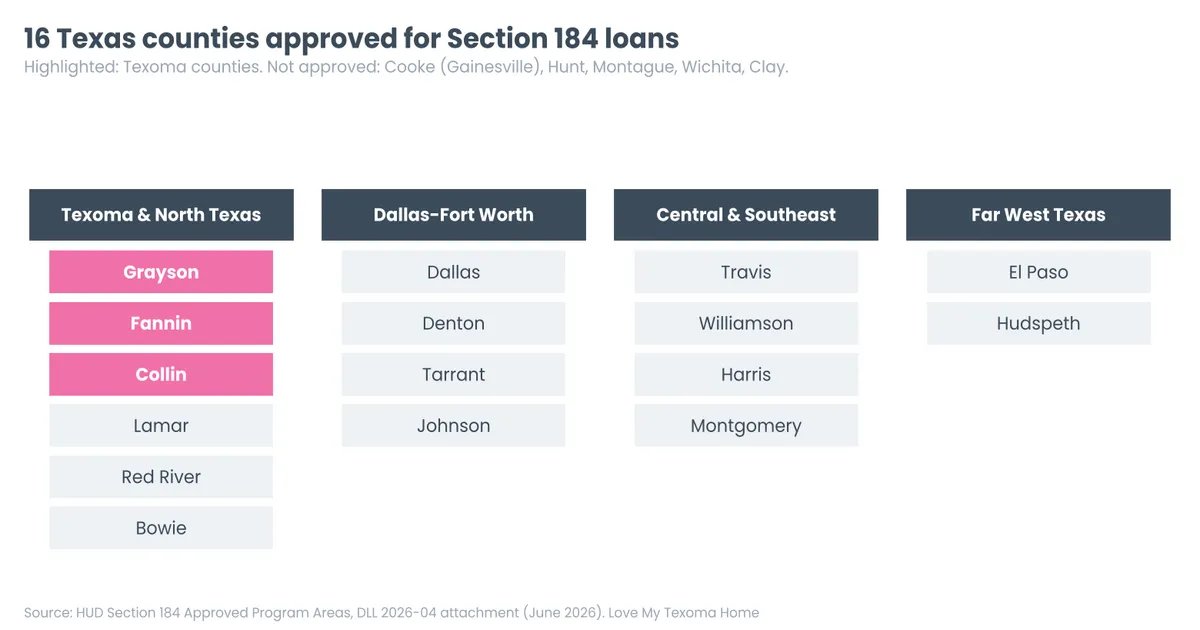
Yes. Section 184 isn't limited to Oklahoma residents. Any enrolled member of a federally recognized tribe can use it to buy a primary home in a HUD-approved area. In Texas, that's 16 counties, including Grayson, Fannin, Collin, Denton, Dallas, Tarrant and Lamar (HUD approved areas, June 2026).
Texas counties approved for Section 184
| Region | Approved counties |
|---|---|
| Texoma and North Texas | Grayson, Fannin, Collin, Lamar, Red River, Bowie |
| Dallas-Fort Worth | Dallas, Denton, Tarrant, Johnson |
| Central and Southeast Texas | Travis, Williamson, Harris, Montgomery |
| Far West Texas | El Paso, Hudspeth |
Not approved near Texoma: Cooke (Gainesville, Valley View), Hunt, Montague, Wichita and Clay counties. HUD added 14 of these Texas counties in August 2023 after two tribes asked for them (HUD DLL 2023-06). Back in 2013, when the Five Civilized Tribes inter-tribal council pushed for DFW coverage, HUD had guaranteed 6,486 Section 184 loans in Oklahoma and only 4 in Texas (Resolution 13-13).
Any tribe can ask HUD to add counties by certifying it has members living there (HUD DLL 2023-02). If you live in Cooke County, ask your tribe about it.
Which tribal programs work for a home in Texas?
| Tribe and program | Works in Texas? | What you get |
|---|---|---|
| Chickasaw down payment grant | Likely yes (open to "Chickasaws At-large") | Up to $5,000 |
| Choctaw Section 184 desk & 5% second mortgage | Yes, in approved Texas counties | 5% for 5 years |
| Choctaw CHAP loan | Possibly; out-of-state loans start with Choctaw Home Finance (580-326-7641) | Tribal mortgage up to 30 years |
| Shawnee Tribe grant | Yes; location doesn't matter | Up to $7,500 |
| Citizen Potawatomi one-time grant | Yes; members anywhere in the U.S. | $2,125 |
| Tonkawa Home Buyers Program | Yes per the 2022 policy; confirm it's still offered | $5,000 |
| Cherokee at-large | Section 184 only; MAP requires a home inside the reservation | — |
| Muscogee (Creek) | No; you must live on the reservation | — |
| Comanche 2025 nationwide expansion | Was open with no service-area limit, but the one-time money ran out within days | Ended |
What's different when you buy on the Texas side
- Texas state down payment programs don't pair with Section 184. TDHCA's My First Texas Home and TSAHC list only FHA, VA, USDA or conventional first loans (TDHCA) (TSAHC). Run the numbers both ways.
- Pick a lender approved for Texas Section 184 loans. On HUD's August 2026 list, BOKF (Bank of Texas), Chickasaw Community Bank, Prosperity Bank, Gateway First Bank, Guild Mortgage and PrimeLending are approved for Texas; First United Bank is approved for Oklahoma only (HUD lender list).
- VA's Native American Direct Loan won't work here. It requires federal trust land, and Texoma's Texas counties have none (VA NADL agreements).
- Texas's own tribes are far away. The Alabama-Coushatta (Polk County), Kickapoo (Maverick County) and Ysleta del Sur Pueblo (El Paso) don't post homebuyer programs for members in North Texas (Kickapoo Housing Authority).
Shopping the Texas side? Browse Sherman, Denison, Pottsboro, Bonham, McKinney and Frisco, or read what your budget buys in Denison.
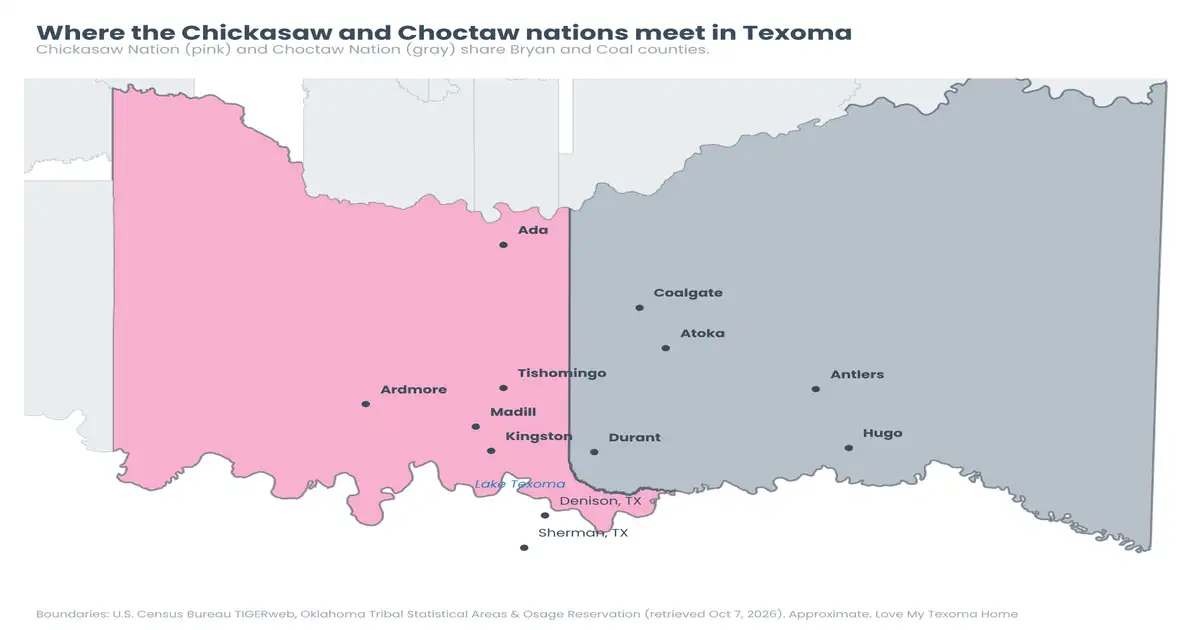
Does the home you want fall in a tribal nation? 🗺️
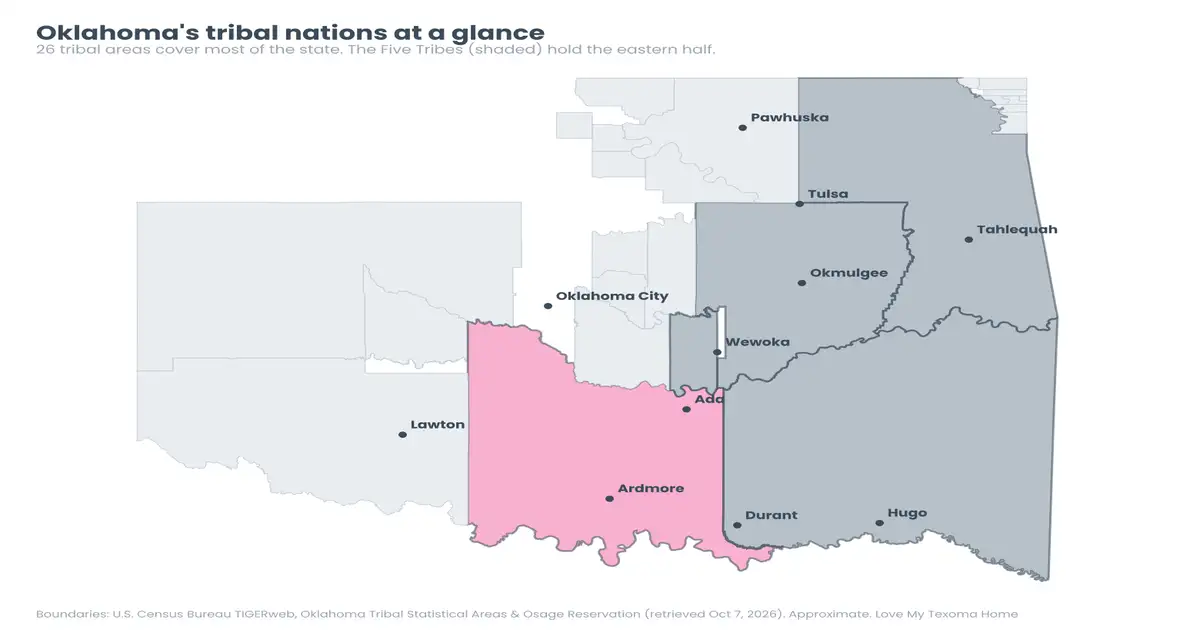
Click any shaded area to see which nation it belongs to, then tap the link in the pop-up to jump straight to that nation's homebuyer programs below. Boundaries are the U.S. Census Bureau's Oklahoma Tribal Statistical Areas plus the Osage Reservation (TIGERweb, retrieved October 7, 2026). They're approximate, so confirm a specific address with the tribe.
Open the map full screen · Remember: for most tribal grants, what matters is your tribe, and for some, whether the home sits inside that tribe's reservation.
Tribe-by-tribe homebuyer programs in Oklahoma 🪶
Oklahoma tribes run more than 20 verified homebuyer programs, from $2,125 grants to $20,000 mortgage assistance. We start with the two nations whose land covers Texoma, then the rest of the Five Tribes, then every other tribe we could verify.
Chickasaw Nation
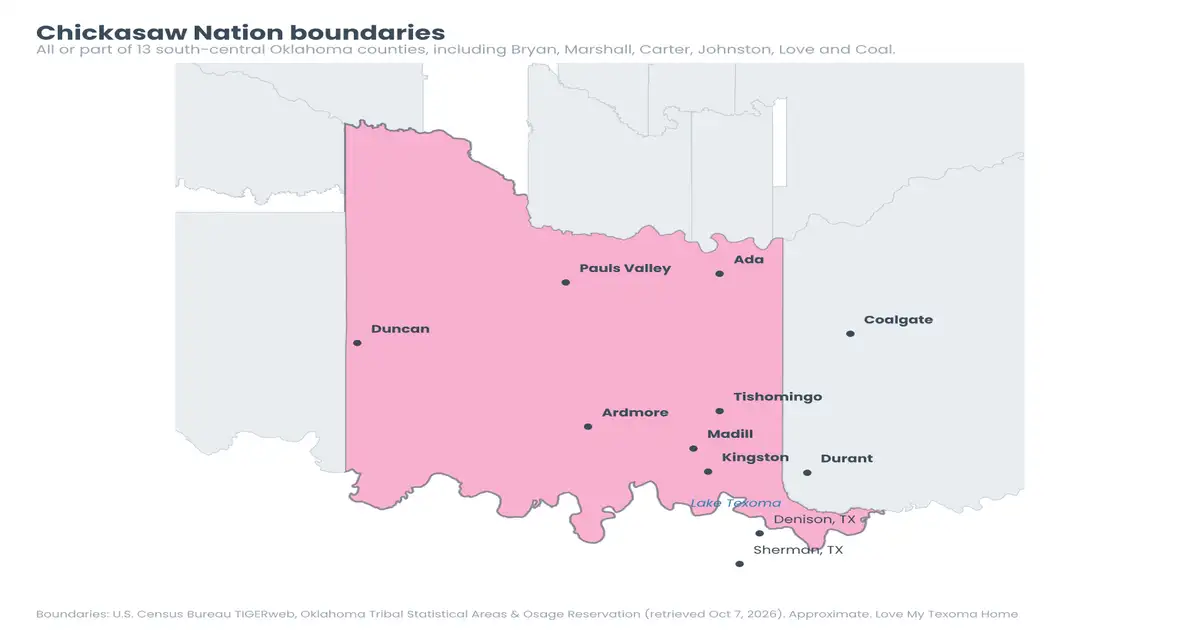
The Chickasaw Nation covers 7,648 square miles across all or part of 13 counties, including Bryan, Marshall, Carter, Johnston, Love and Coal (Chickasaw Nation). That's home to Ardmore, Madill, Kingston, Tishomingo and the capital, Ada. Its down payment grant is one of the few that follows citizens out of state, which matters if you're buying in Sherman or Denison. It's also the program I know firsthand as a Chickasaw citizen.
Down Payment and/or Closing Cost Assistance Grant
- What you get: a one-time grant of up to $5,000. The Nation's FY2025 report shows more than 500 citizens received $2.58 million, about $5,160 each (Chickasaw grant page) (2025 Progress Report). Confirm the current amount before you budget.
- Who qualifies: Chickasaw citizens named on the loan, approved for a home loan, buying a primary residence. Rate-and-term refinances count; cash-out refinances don't. The page lists no income limit and serves "Chickasaws At-large."
- How to apply: submit the (online application) with your citizenship card, pre-approval letter and loan application at least 3 weeks before closing. It won't pay after closing.
- Contact: Housing Counseling and Loan Services, (580) 421-8800.
Homeowners Program (new homes for ownership)
- Newly built homes for First Americans, with preference for Chickasaws. Income at or below 100% of U.S. median, assets under $20,000, and you must live inside the Chickasaw service area (Chickasaw Homeowners Program).
Housing Counseling Services
- Free pre-purchase coaching on credit and budgeting for residents and at-large citizens (Chickasaw counseling). After you buy, look at the Home Improvement Grant (up to $7,500) and Homeowner Preparedness Grant (up to $5,000) (Chickasaw Housing).

Choctaw Nation of Oklahoma
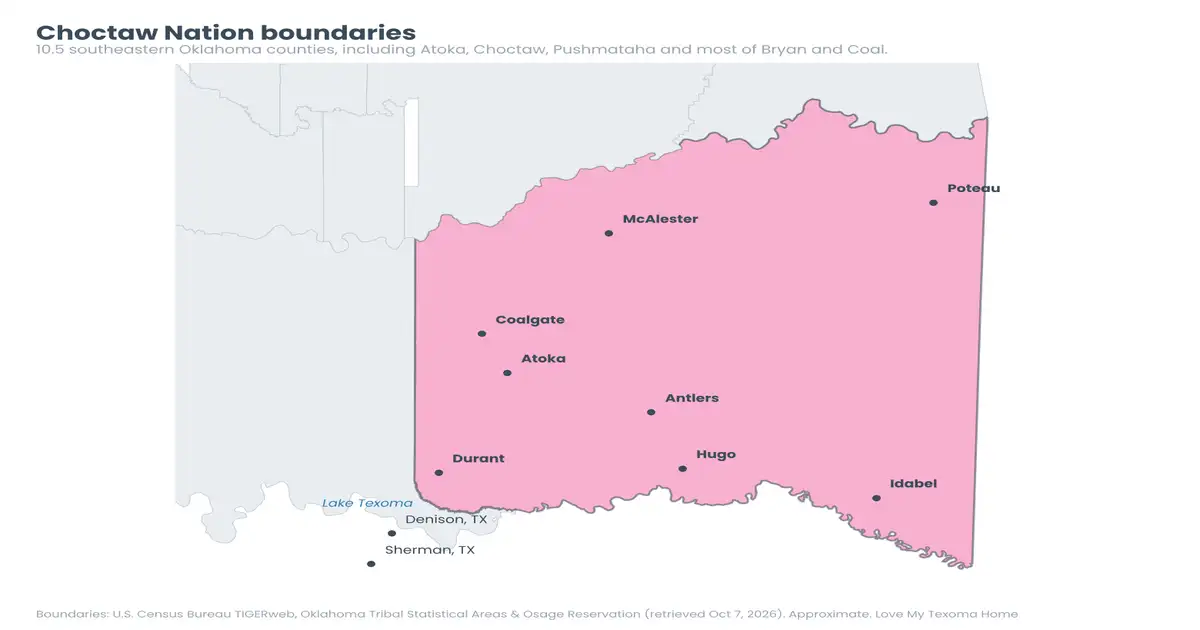
The Choctaw reservation includes Atoka, Choctaw and Pushmataha counties in full and most of Bryan and Coal. That takes in Durant, Calera, Atoka, Hugo, Antlers and Coalgate. Choctaw Home Finance in Hugo is the tribe's own lender. New to the area? Read Durant, Oklahoma: the Gateway to Lake Texoma and our Hugo community guide.
Choctaw Homebuyer Advantage Program (CHAP)
- What you get: a home loan from the tribe with terms up to 30 years, approved on credit and debt ratios. No maximum income. Rates and amounts aren't published; funds are first come, first served.
- Who qualifies: Choctaw tribal members. Out-of-state loans must start with Choctaw Home Finance (CHAP). 580-326-7641.
Down Payment/Closing Cost Assistance
- What you get: a second-mortgage loan, not a grant, at 5% for up to 5 years, stackable on Section 184 (Choctaw cost assistance).
- How to apply: online at the (Choctaw Home Finance portal) or by mail to 403 Chahta Circle, Hugo, OK 74743. 580-317-9610 or 800-235-3087.
LEAP (Lease to Purchase)
- A newly built 3- or 4-bedroom brick home on a 15-year lease with homebuyer counseling; in year 16 you finance the balance. Income band example: $52,100 to $93,780 for a family of four (Choctaw LEAP). Apply at the (LEAP application).
The Choctaw Revolving Loan Fund also offers micro-loans of up to $2,500 for emergency home repairs inside the service area (Choctaw RLF).

Cherokee Nation
Mortgage Assistance Program (MAP)
- What you get: up to $20,000 for down payment and closing costs, plus credit coaching, as a soft second mortgage.
- Who qualifies: members of any federally recognized tribe (Cherokee preference); no home owned in 3 years; income at or below 80% of median ($59,850 for 1 person, $85,450 for 4, $112,800 for 8); home inside the Cherokee reservation, under 5 acres; HACN homebuyer class required.
- How to apply: mail the (MAP application) to HACN, PO Box 1007, Tahlequah, OK 74465. 918-456-5482 (HACN MAP).
New Home Construction (lease-to-own)
- HACN builds a home on land you own inside the reservation; you pay a fixed lease for 30 years, then the deed is yours (HACN).

Muscogee (Creek) Nation
Mortgage Down Payment & Closing Cost Program
- A grant toward down payment and closing costs (amount not published) for first-time buyers living within the Muscogee (Creek) Reservation, income between 50% and 80% of national median. Mail the (pre-application) to P.O. Box 297, Okmulgee, OK 74447. (918) 549-2529 (MCN Housing).
Lease With Option to Purchase
- Lease a Nation-owned home; after 25 years it's yours. Requires at least $20,000 a year in income and a Creek card or CDIB from any federally recognized tribe (MCN homeowner programs).

Seminole Nation of Oklahoma
Down Payment and Closing Cost Assistance
- Up to 10% of the price, capped at $15,000, forgiven after 5 years in the home. Open to members of any federally recognized tribe or Seminole Freedmen (Seminole priority), income at or below 80% of median, buying in the Seminole service area; counseling required. (405) 257-6604 (HASNOK).
Lease Purchase Homeownership
- Rent set at about 25% of adjusted income, with the home transferred after you complete the program (HASNOK).
Every other Oklahoma tribe with a verified homebuyer program
Sorted by the largest published benefit. "Not published" means the program is real but the tribe doesn't post an amount, so call.
| Tribe | Program | Benefit | Key rules | Contact |
|---|---|---|---|---|
| Citizen Potawatomi Nation | Mortgage Buy-Down; One-Time Grant | $20,000 buy-down; $2,125 grant | Buy-down: CPN members in CPN jurisdiction, at or below 80% of median, loan through Sovereign Bank. Grant: CPN members anywhere in the U.S. | 405-273-2833 |
| Peoria Housing Authority (Peoria & Ottawa) | Down payment & closing cost grant | Up to $18,000 | Low-income Peoria and Ottawa citizens first, then other Native buyers; home within 75 miles of Miami, OK; 5-year lien | 918-542-1873 |
| Comanche Nation Housing Authority | Down payment grant; Homeownership Lease Purchase | Up to $15,000 grant; lease-purchase with $50,000 off and 0% interest | Comanche members within income limits; Caddo, Comanche, Cotton, Kiowa, Tillman (plus Grady, Stephens) counties; HomeView class required | (580) 357-4956 |
| Shawnee Tribe | Down payment & closing cost grant | Up to $7,500 | Shawnee Tribe citizens 18+; any income, any location | (918) 542-2441 ext. 135 |
| Eastern Shawnee Tribe | First Time Homeowners Assistance | Up to $7,500 (an older policy says $10,000) | Enrolled first-time buyers 18+; no income limit | [email protected] |
| Otoe-Missouria Tribe | Homebuyer Assistance (THBA) | Up to $6,000 | Rules not posted online | 580-723-4466 ext. 345 |
| Osage Nation | Down payment assistance | $5,500 grant (2020 policy) | Any Native buyer in Oklahoma, Osage preference; at or below 80% of median with higher-income tiers | 918-287-5310 |
| Tonkawa Tribe | Home Buyers Program | $5,000 one-time grant | Tonkawa members; no income limit; home can be anywhere; live there 2 years | (580) 628-2561 |
| Iowa Tribe (Bah-Kho-Je) | Down payment & closing cost help | Up to $5,000, once per lifetime | Already approved by a participating lender | (405) 547-2402 ext. 2901 |
| Delaware Tribe of Indians | Down Payment Assistance (ARPA); Homeownership Opportunity Program | Up to $5,000; 30-year lease-purchase | DPA for Delaware members (COVID-relief funded, may be used up); lease-purchase at 50% to 80% of median | 918-337-6572 |
| Sac and Fox Nation | Lease Option Housing | 25-year lease with option to buy anytime | Low-income members first; payment at most 30% of income | (405) 275-8200 |
| Caddo Nation | Down payment assistance; lease with option to purchase | Not published | Enrolled Caddo citizens; FY2026 limits $59,850 (1 person) to $112,800 (8) | (405) 480-2100 |
| Kiowa Housing Authority | Down payment & closing cost | Not published (opened Jan 15, 2026) | CDIB, income proof, lender documents | 405-339-8100 |
| Kaw Nation | Down payment assistance | Not published | Kaw citizens buying in Oklahoma | (580) 362-6264 |
| Wyandotte Nation | Down payment & closing cost | Not published | First-time buyers; $58,352 to $110,035 income limits; within 50 miles of Wyandotte, OK | (918) 678-6336 |
| Absentee Shawnee Housing Authority | Mortgage Assistance Program | Not published | Enrolled Absentee Shawnee members | (405) 273-1050 |
| Cheyenne & Arapaho Tribes | Down payment assistance | Not published; $15,000 stipends planned for members slightly over HUD limits | Policy on the housing page | (580) 331-2400 |
| Seneca-Cayuga Nation | Down payment assistance | Not published | Member preference; within 50 miles of Grove | (918) 787-5452 |
| Modoc Nation | Down payment assistance | Not published | Modoc first-time buyers | 918-542-8175 |
| Ponca Tribe | Down payment & closing cost; lease-purchase | Not published | Application dated Feb 2026 | (580) 762-5909 |
| United Keetoowah Band | Down payment & closing cost | Not published | Low-income first-time UKB buyers | 918-871-2773 |
| Fort Sill Apache | Down payment & closing cost | Not published | Contact the housing director | 580-588-2298 ext. 2263 |
| Wichita and Affiliated Tribes | Mutual Help; Section 184 rent-to-assume | No grant | Rent-to-assume for members over income limits | 405-247-7470 |
No homebuyer program found online (as of October 7, 2026): Miami Tribe, Pawnee Nation, Apache Tribe of Oklahoma, Quapaw Nation, Kickapoo Tribe (low-rent and home ownership units only), and the Thlopthlocco, Alabama-Quassarte and Kialegee Tribal Towns. Call your tribe's housing office anyway; programs open and close with funding. Members of these tribes can still use Section 184.
Other federal and state programs Native buyers can use 🏛️
Section 184 isn't the only door. These programs are open to Native buyers too; some are Native-only, some are for everyone.
| Program | What it gives | Who qualifies | Best fit |
|---|---|---|---|
| VA Native American Direct Loan | Direct VA loan, no down payment in most cases, no PMI; rate "starts at 2.47%" | Native veterans, or non-Native veterans married to a Native spouse | Trust or restricted land under a tribe with a VA agreement (Osage, Cherokee) |
| USDA 502 Direct | 5.75% as of Oct 1, 2026; payment help as low as 1%; usually no down payment | Low and very-low income | Rural Bryan, Marshall, Atoka and Johnston counties |
| USDA 502 Guaranteed | 100% financing; 1% upfront and 0.35% yearly fee | Income up to 115% of area median | Rural homes; check the USDA eligibility map |
| BIA Housing Improvement Program | Repairs up to $7,500, renovation up to $60,000, or a modest replacement home | At or below 150% of poverty guidelines, substandard housing | Very-low-income repairs, not a typical purchase |
| OHFA Homebuyer DPA | 3.5% of the loan, 0% deferred second | 640+ credit | Oklahoma buyers using FHA, VA or USDA |
| TSAHC | Up to 5% grant or forgivable second | 620+ credit | Texas buyers using FHA, VA, USDA or conventional |
| ONAC down payment assistance | Up to $14,000 | Native buyers at or below 80% of median in certain disaster-declared Oklahoma counties, with extra household criteria | Ask whether your county qualifies; (405) 720-0770 |
| FHLB Topeka HSP | Up to $15,000 | First-time buyers at or below 80% of median | 2026 round closed; next expected around March 2027 |
Behind the scenes: most tribal grants are paid for by HUD's Indian Housing Block Grant under NAHASDA, which is why so many cap income at 80% of median (NLIHC Advocates' Guide). FHLB Topeka's Native American Housing Initiative sent about $3.6 million to 12 Oklahoma tribes in 2025 (FHLB Topeka).
Your Texoma game plan 🧭
The right stack depends on two things: your tribe and which side of the Red River you're buying on.
| You are | Buying in | Best first mortgage | Help you can stack |
|---|---|---|---|
| Chickasaw citizen | Oklahoma side (Durant, Ardmore, Madill, Kingston) | Section 184 | Chickasaw grant up to $5,000; Homeowners Program if under 100% of median |
| Chickasaw citizen | Grayson or Fannin County (Sherman, Denison, Bonham) | Section 184 | Chickasaw grant up to $5,000 (at-large citizens) |
| Choctaw member | Oklahoma side (Durant, Atoka, Hugo) | Section 184 or CHAP | Choctaw 5% second mortgage; LEAP lease-to-own |
| Choctaw member | Grayson, Fannin or Collin County | Section 184 or CHAP (call Choctaw Home Finance first) | Choctaw second mortgage where the lender allows |
| Any tribe | Gainesville (Cooke County) | FHA or USDA (Section 184 isn't approved) | TSAHC or TDHCA down payment help |
| Native veteran | Restricted or trust land in Oklahoma | VA NADL (if your tribe has a VA agreement) | Tribal grants |
| Over the income limits | Anywhere approved | Section 184 (no income cap) | Chickasaw grant, Choctaw CHAP, Tonkawa and Shawnee Tribe grants |
Timeline from "thinking about it" to keys
- 3 to 6 months out: get your tribal card and CDIB in order, take a homebuyer class, and clean up credit.
- 2 to 3 months out: get pre-approved with a Section 184 lender and ask your tribe for its current grant amount and deadlines.
- Under contract: submit the tribal grant packet immediately. Chickasaw needs 3 weeks; Seminole wants loan approval 45 days before closing (HASNOK policy).
- Closing: the grant goes straight to the title company.
- After closing: keep the home as your primary residence. Several grants (Seminole 5 years, Peoria 5 years, Tonkawa 2 years) must be repaid if you sell or move out early.
Budgeting? Browse homes under $100K, $100K to $200K, $200K to $300K and $300K to $400K, read affordable homes in Durant under $200K, or check land under 5 acres if you want to build.
Our partner lenders who can do Section 184 loans 🏦
These lenders from our Texoma Preferred Lenders & Vendors network offer Section 184 loans. Read each lender's spotlight below, then ask about turn times and how they pair Section 184 with your tribe's down payment help.
Meet Our Section 184 Lenders
Also HUD-approved: Brooke Fields, Mortgage Loan Consultant with First United Bank Mortgage Group in Durant (NMLS #1484840), (580) 367-0593. First United is approved for Section 184 on Oklahoma homes (HUD, updated Aug 4, 2026).
You choose: you're always free to use any lender you like, and we don't receive compensation for referrals. HUD's full (Section 184 approved lender list) shows every approved lender by state.
Frequently asked questions ❓
What is the minimum down payment on a Section 184 loan?
Does a Section 184 loan have mortgage insurance?
What credit score do I need for a Section 184 loan?
Is there an income limit for Section 184?
Can I use a Section 184 loan in Texas?
Are Native American home loans only for Oklahoma residents?
Can my non-Native spouse be on the loan?
Can I buy a lake house or rental with Section 184?
Do I need a CDIB card to get a Section 184 loan?
Can I get Chickasaw down payment assistance if I live in Texas?
Which Oklahoma tribe offers the most down payment help?
Can I combine a tribal grant with Section 184?
Can I get a tribal grant after I close?
Ready to see what you qualify for? 🤝
If you haven't picked an agent yet and you're thinking about buying in Texoma, we'd love to help. As a Chickasaw citizen who's been through these programs, Brian will help you line up Section 184, your tribe's grant and the right lender, and build the deadlines into your contract.
Call or text (580) 217-7435 Meet Brian & JonelleSources
- HUD: Section 184 for borrowers
- HUD: Section 184 approved lenders, Aug 4, 2026
- HUD: Section 184 approved areas map, June 2026
- HUD: DLL 2026-02, 2026 loan limits
- HUD: DLL 2026-01, compliance date
- HUD: DLL 2023-06, Texas expansion
- HUD: Processing Guidelines Ch. 2-B
- Federal Register: Strengthening Section 184, Mar 20, 2024
- FDIC Affordable Mortgage Lending Guide: Section 184
- Chickasaw Nation: down payment grant
- Choctaw Nation: CHAP
- Choctaw Nation: Section 184
- Housing Authority of the Cherokee Nation: MAP
- Muscogee (Creek) Nation Housing
- HASNOK (Seminole Nation) down payment assistance
- VA Native American Direct Loan
- TDHCA My First Texas Home matrix
- U.S. Census Bureau TIGERweb (map boundaries)
Disclaimer: Information in this guide is accurate as of October 7, 2026, based on each program's official page on that date. Tribal and government housing programs change amounts, income limits and deadlines often, and funds can run out mid-year. Confirm current terms directly with the tribe, agency or lender before you rely on them. Love My Texoma Home is a real estate team, not a lender or tribal agency, and nothing here is legal, tax or financial advice. Love My Texoma Home Team, a team of INC Realty.
More for Texoma Homebuyers
View More Blogs


Guides & Resources
For Buyers
Buying a Home in TexomaFirst-Time Home Buyer ProgramsNative American Homebuyer ProgramsThe Closing ProcessNew Construction GuideBuying Land & AcreageLenders & Local Pros