New - 15 Mins Ago




Your credit score is one of the biggest factors in whether you qualify for a mortgage, what loan programs you're eligible for, and how much you'll pay in interest over the life of your loan. In simple terms, a higher credit score signals to lenders that you're a lower-risk borrower, which typically unlocks lower minimum down payments and better interest rates, while a lower score can mean higher rates, larger down payment requirements, or even a declined application. Understanding how credit works before you start house hunting near Lake Texoma can save you thousands of dollars and a lot of stress.

Captain N.A. Birge House, Sherman. Photo: HominyGrits007 via Wikimedia Commons (CC0)
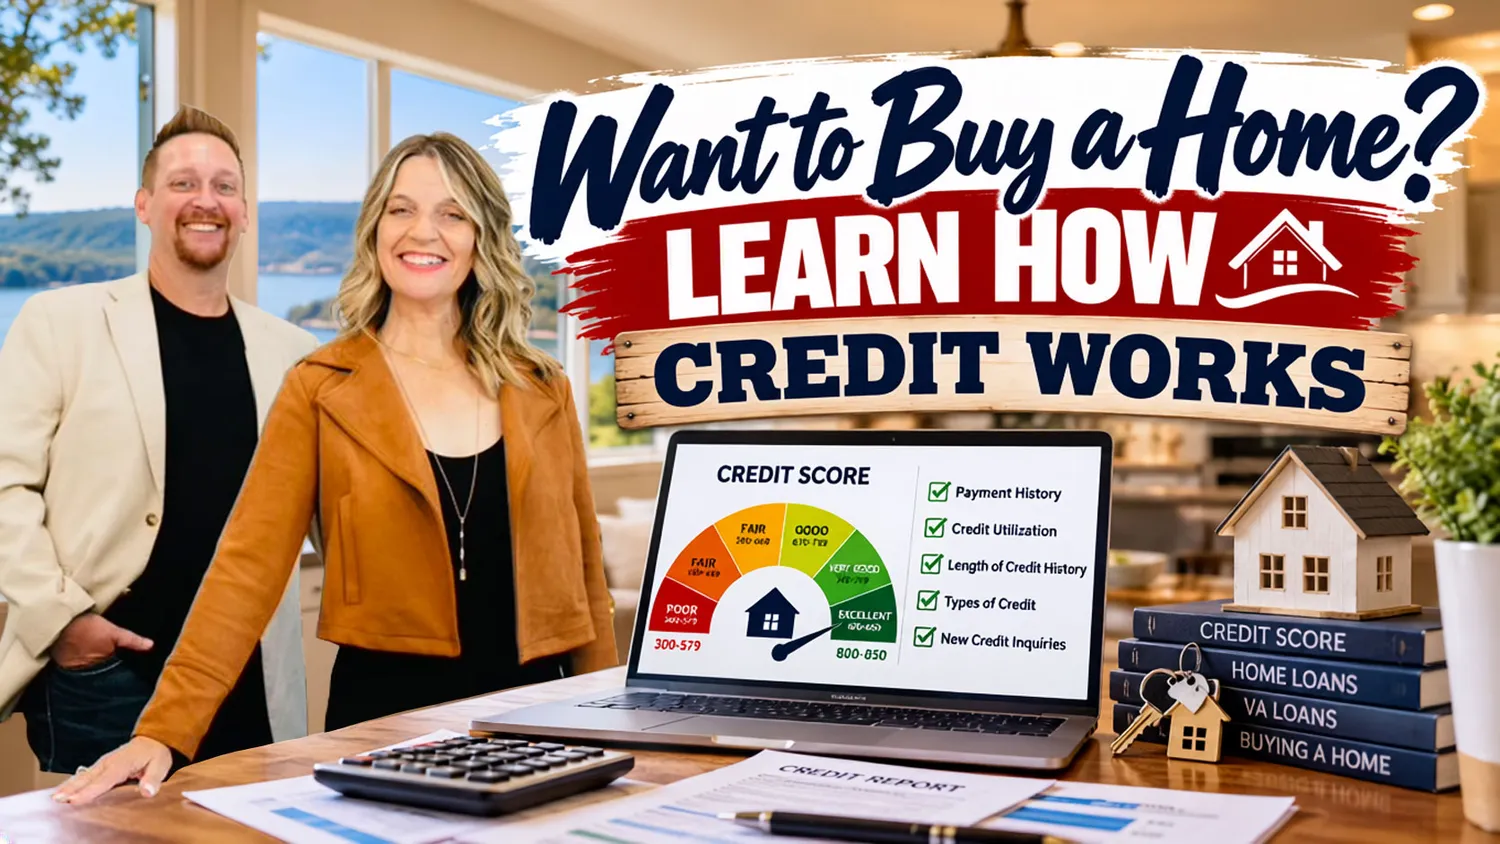
Most mortgage lenders rely on your FICO score, which ranges from 300 to 850 and is built from five weighted categories:
This is the single biggest factor. On-time payments on credit cards, auto loans, student loans, and other debts build your score, while late payments, collections, and bankruptcies drag it down significantly.
This measures how much of your available revolving credit you're using. Maxed-out credit cards hurt your score even if you pay on time, because lenders want to see that you aren't overextended.
The longer your accounts have been open and in good standing, the better. This is why financial advisors generally recommend keeping older accounts open rather than closing them.
Lenders like to see that you can responsibly manage different types of credit, such as a mix of credit cards, an auto loan, and installment debt.
Opening several new accounts in a short period, or having multiple hard inquiries, signals higher risk and can temporarily lower your score.
Once you understand how the score is built, the next question is: what score do you actually need to buy a home? Requirements vary by loan program and by individual lender overlays, but here are the general industry benchmarks.
Conventional loans backed by Fannie Mae or Freddie Mac typically require a minimum credit score of around 620. Borrowers with scores of 740 or higher usually receive the most favorable pricing and lowest down payment options.
FHA loans are popular with first-time buyers because they're more flexible on credit. You can often qualify with a score as low as 580 for the standard 3.5% down payment, and some lenders will go as low as 500 with a larger 10% down payment.
The VA itself doesn't set a hard minimum credit score for eligible veterans, active-duty service members, and surviving spouses, but most lenders who fund VA loans look for a score of at least 580 to 620.
USDA loans, designed for eligible rural and suburban properties (which cover many communities around Lake Texoma), generally call for a credit score of 640 or higher for automated approval, though manual underwriting is sometimes possible below that threshold with strong compensating factors.

West Sears Street, Denison. Photo: Michael Barera, CC BY-SA 4.0, via Wikimedia Commons
Credit score for mortgage approval is only half the story. Lenders use risk-based pricing, meaning your rate is adjusted based on where your score falls within specific tiers. A borrower with a 760+ score might receive a noticeably lower rate than someone with a 640 score on the exact same loan amount and property. Over a 30-year mortgage, even a half-point difference in your interest rate can add up to tens of thousands of dollars in extra interest, which is why lenders and real estate agents alike encourage buyers to strengthen their credit before shopping for a loan, not after they've already found their dream home.
If your score isn't quite where you want it, there's usually time to improve it before you apply. Practical, proven steps to improve credit before buying a house include:
Pay down credit card balances. Aim to keep utilization under 30%, and ideally under 10%, on each card.
Pay every bill on time. Set up autopay or reminders, since payment history carries the most weight.
Don't open new credit accounts. Avoid financing furniture, appliances, or a new car in the months before applying for a mortgage.
Leave old accounts open. Closing a long-standing card can shorten your average credit history and raise your utilization ratio.
Check your credit report for errors. Dispute any inaccurate late payments, incorrect balances, or accounts that aren't yours through all three credit bureaus.
Avoid co-signing new loans. Any new debt, even for someone else, shows up on your report and affects your debt-to-income ratio.
A lot of buyers delay their home search because of credit misinformation. Here are a few myths worth clearing up:
Myth: Checking your own credit hurts your score. Reviewing your own report is a soft inquiry and has no effect on your score.
Myth: You need to carry a balance to build credit. Paying your card off in full every month is actually better for your score and your wallet.
Myth: Closing old cards helps your score. It often does the opposite by shortening your credit history and raising utilization.
Myth: All debt is treated the same. Revolving debt like credit cards affects utilization differently than installment loans like auto or student loans.
Mistake: Applying for a mortgage before checking your credit. Surprises during underwriting can delay or derail a closing, so it pays to review your credit months in advance. If you're weighing a purchase near the lake, it's also worth reading up on how to work with a local Realtor when buying near Lake Texoma, since a good agent can connect you with lenders who specialize in exactly these situations, and understanding what contingencies to include when buying a home on Lake Texoma so your financing stays protected while you strengthen your credit picture.
Getting mortgage-ready doesn't have to be a solo project. Brian & Jonelle Allen work with a trusted network of local and regional lenders who can pull your credit, walk you through exactly where you stand, and map out a realistic timeline to get you pre-approved. Whether you're a few points away from qualifying or ready to go today, reach out to Brian & Jonelle to talk through your credit, your loan options, and your next steps toward owning a home in the Texoma area.
Most conventional loans require a minimum score around 620, FHA loans allow scores as low as 580 (or 500 with a larger down payment), and USDA loans generally look for 640 or higher. VA loans have no official minimum, but most lenders want to see at least 580 to 620.
Lenders use tiered, risk-based pricing, so a higher score typically qualifies you for a lower rate. The difference between a 620 score and a 760+ score can equal tens of thousands of dollars in interest over a 30-year loan.
Meaningful improvement can happen in as little as 30 to 90 days if you pay down credit card balances and avoid new debt, though building a longer credit history or recovering from major negative marks like a collection or bankruptcy can take a year or more.
No. Checking your own credit report or score is considered a soft inquiry and does not lower your score. Only hard inquiries from lenders during an actual loan application affect your score, and typically only by a few points.
It's possible but more limited. Some lenders offer manual underwriting using alternative credit sources like rent, utility, and insurance payment history, which is more common with FHA and USDA loans than conventional financing.


Guides & Resources
For Buyers
Buying a Home in TexomaFirst-Time Home Buyer ProgramsNative American Homebuyer ProgramsThe Closing ProcessNew Construction GuideBuying Land & AcreageLenders & Local Pros